
Roughly one in five injury claims I hear about from Gulf Coast workers doesn’t belong in the state workers’ comp system at all. It belongs in maritime law, and the difference changes everything about how the claim gets filed, how long it takes, and how much it pays.
Most people assume there’s one path after a workplace injury in Louisiana. There are two, and the line between them runs through the docks, the rigs, and the supply boats that keep the Port of New Orleans moving. If you work on or near the water, you need to know which system covers you before you sign anything or file anything.
Here’s the short version. If your job ties you to a vessel or to navigable water in a real, ongoing way, you’re probably outside the standard workers’ comp track. If your job merely happens to sit near the river, you’re probably inside it. This piece walks through the difference, the traps, and what to do in the first 72 hours.
Why the Gulf Coast Isn’t a Normal Workers’ Comp Market
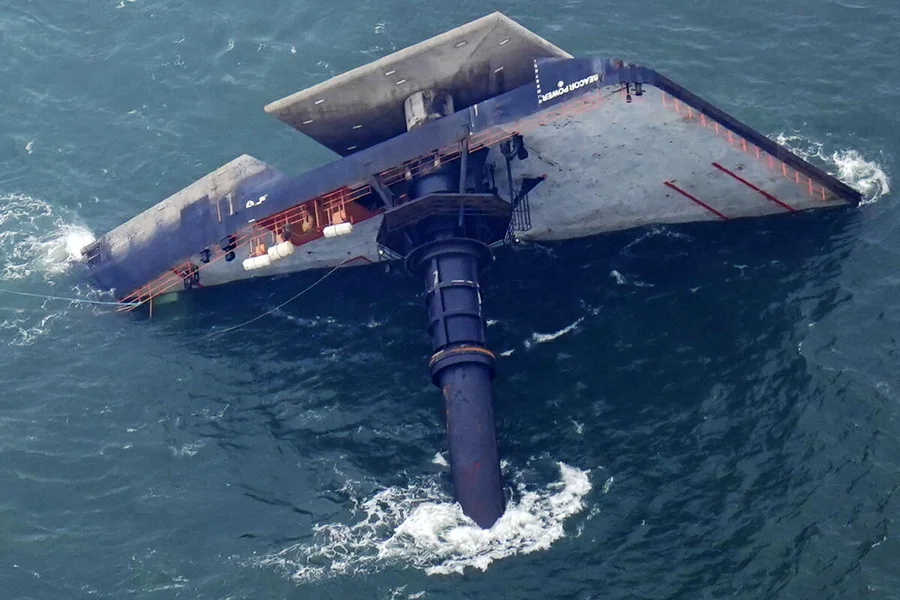
Louisiana has one of the largest concentrations of maritime employment in the country. Pilots, deckhands, riggers, welders, cooks on crew boats, and the warehouse crews that load them all work within a few miles of each other, but they don’t share the same legal protections. A stevedore on the dock and a deckhand on the vessel parked next to him can get hurt on the same afternoon and end up in completely different systems.
That matters because the systems pay differently. State workers’ comp in Louisiana generally covers medical care and weekly wage benefits at a rate set by statute. Maritime claims under general maritime law or the Jones Act can include damages beyond wage replacement, which is a wider net than most people expect.
If you’re a dockworker, a longshoreman, or a harbor worker who never leaves the land but works over water, your claim usually runs through the Longshore and Harbor Workers’ Compensation Act, a federal program that sits between the two. According to the U.S. Department of Labor, that act covers a specific category of maritime employees who are injured on navigable waters or adjoining areas. Knowing which bucket you fall in is the single most important fact in your claim.
The trap is that employers and their carriers sometimes guess, and they guess in the direction that costs them less. Don’t let them make that call for you.
Vessel Crew, Dock Crew, or Shore Crew?
Ask yourself three questions and the answer usually appears.
- Does your job take you onto a vessel or onto navigable water as a regular part of the work, not as a one off?
- Do you contribute to the mission of that vessel, whether that’s hauling cargo, moving crew, or servicing a platform?
- Does your employer control your work down to the hour, or does the vessel’s captain?
Three yeses lean maritime. Three noes lean standard workers’ comp. Mixed answers are exactly why this gets argued, and they’re why the first phone call you make after an injury tends to shape the next two years.
I’d rather see a worker get the category wrong and correct it in week one than get it “roughly right” and sign a settlement under the wrong statute. Correcting a classification after you’ve signed is close to impossible. Correcting it before you’ve filed anything is routine.
What Happens in the First 72 Hours
The first three days decide more than most people realize. Your medical records and your written account of the accident are the two things the other side will pick apart first, and both are easiest to get right immediately after the injury.
- Report the injury in writing, not verbally, and keep a copy. A text to your supervisor counts, but email is better.
- Get examined and describe your symptoms completely, including anything that seems minor. Unmentioned pain becomes a pre existing condition in someone else’s file.
- Photograph the location, the equipment, and any unsafe condition while it still looks the way it looked when you got hurt.
- Write down the names of everyone who saw it happen, including the deckhand who was two feet away and the guy on the next barge.
- Don’t give a recorded statement to an insurance adjuster before you’ve talked to someone who knows the difference between the two systems.
That fifth point isn’t paranoia. Adjusters ask questions designed around state workers’ comp when the worker is actually covered by maritime law, and the answers given in those first calls get used later to argue the worker already accepted the narrower system.
Employers are also required to keep workplaces reasonably safe. The Occupational Safety and Health Administration sets the baseline for that duty in most Gulf Coast operations, and a documented safety violation often becomes the spine of a maritime case.
The Weather Angle Nobody Plans For
Gulf Coast work is seasonal in ways that inland jobs aren’t, and that shapes claims in a way that surprises people. Hurricane season reshuffles crews, extends hitches, and pushes vessels into unfamiliar water with tired crews. Winter fronts do something similar on the supply runs.
According to the National Oceanic and Atmospheric Administration, the Atlantic hurricane season runs from June through November each year, with the busiest stretch typically arriving in late summer. That cycle means injuries cluster in ways that don’t match a normal calendar year, and it means witnesses scatter when a crew rotates out.
I’ve watched a claim fall apart because the only two people who saw the accident shipped out on different boats three days later and couldn’t be located until the following spring. Collecting contact information in the first week isn’t busywork. It’s the whole case.
A Simple Rule I’d Give Any Gulf Coast Worker
Here’s the framework I’d hand to a friend on the docks, and I’ve never seen it lead someone wrong. Call it the three layer test. Layer one is where the injury happened. Layer two is what your job requires of you on a typical shift, not on the day of the accident. Layer three is who controlled the work at the moment it went wrong.
If all three layers point the same direction, you know your system. If they split, you’ve got a real question that deserves a professional read before you file anything. The statute of limitations for maritime claims is different from the state deadline, and it’s shorter than most workers assume.
That’s the kind of detail a workers comp attorney in New Orleans deals with every week, and it’s the reason the first consultation is worth more than the filing fee ever will be.
One more stance: I’d take the maritime classification seriously even when it looks borderline, because the remedies tend to be broader and the burden on the employer is higher. Workers who assume they’re in the standard system and stay quiet usually find out later that they gave up options they never knew they had.
What to Do If You’re Not Sure Which System Covers You
Assume you’re covered by something until proven otherwise. Report the injury. Get the exam. Keep the paperwork. Then get a read on the classification before you sign a single document, especially anything with the words “final” or “release” in the title.
The Gulf Coast runs on boats, docks, and crews that don’t stop for much. The system that protects you when something goes wrong shouldn’t be a guess. Which of the three layers in that test would you have the hardest time answering honestly?